
Weekly Market Insights
October 16, 2026 Volume 13 Issue 40
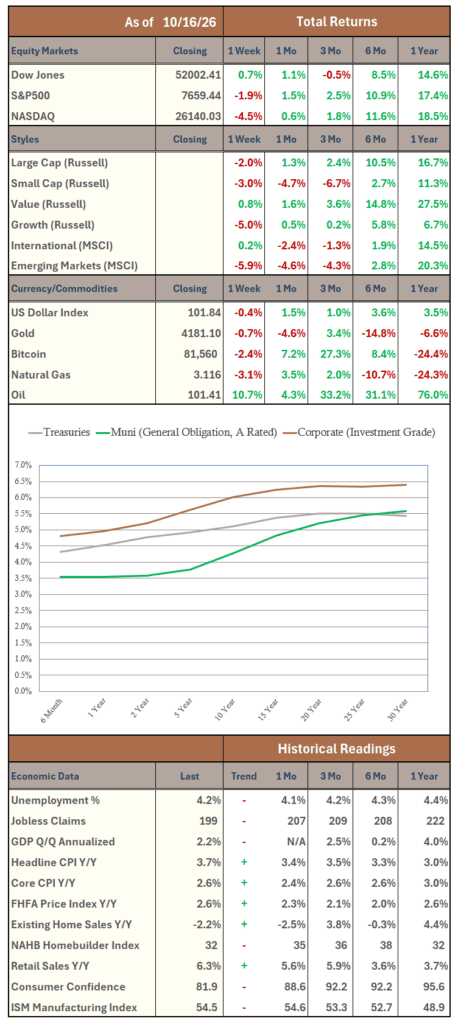
U.S. equity leadership favored value and broader participation, with equal-weighted stocks ahead of the broader index and large caps outperforming small caps. Consumer Staples and Energy led, while Technology trailed. Developed international markets proved more resilient than emerging markets. Fixed income favored longer maturities, municipals, and investment-grade credit over high yield, alongside a generally upward-sloping Treasury curve. Elsewhere, oil led commodities, while REITs stood out among alternatives.
September inflation exceeded expectations, with consumer prices rising 3.7% from a year earlier versus 3.0% wage growth, extending a multi-month erosion of purchasing power. Lower-income households remained especially exposed because necessities absorb more of their budgets. Economic expansion extended across sectors, despite the heavy concentration of recent equity market gains. Third-quarter S&P 500 earnings growth is currently tracking at 29.6% year over year per FactSet, with management guidance remaining broadly constructive relative to recent quarters.
Higher inflation strengthened the case for another Fed increase to restrain demand, but Chair Kevin Warsh avoided signaling October’s decision — consistent with his stated aversion to forward guidance — and markets interpreted his silence as pointing toward a hold. Governor Christopher Waller noted that higher Treasury yields were cooling housing and automobile demand. Greater reliance on Treasury bills lowered funding costs while increasing exposure to changing rates as debt matured.
Energy and AI investment continued to expose supply and financing constraints. Attacks around Hormuz disrupted commercial shipping, with freight and war-risk insurance lifting delivered oil costs and reinforcing inflation pressures. Diesel inventories remained depleted amid supply shortfalls. AI funding capacity varied: major hyperscalers entered 2026 with substantial cash and established businesses, while Oracle issued considerable debt — including a $25 billion bond sale earlier this year — to meet future demand.
Have a great week!
The data and commentary provided herein is for informational purposes only. No warranty is made with respect to any information provided. It is offered with the understanding that Hilltop Holdings Inc., PlainsCapital Corporation, Hilltop Securities and PlainsCapital Bank (collectively “PCB”) are not, hereby, rendering financial and/or investment advice, and use of the same does not create any relationship with PCB. This is neither an offer to sell nor a solicitation of an offer to buy any securities that may be described or referred to herein. PCB does not provide tax or legal advice. Please consult your own tax or legal advisor regarding your specific situation. Whether any of the information contained herein applies to a specific situation depends on the facts of that particular situation. Investment and estate planning and management decisions may have significant financial consequences and should be made only after consulting with professionals qualified to offer legal, accounting and taxation advice. Neither this document nor any portion of its content’s supplements, amends or modifies any account agreement with PCB. Unless otherwise noted:
*All economic release data referenced from public sources believed to be accurate. *The source of data for all charts/graphs included in this presentation is Bloomberg LP. *Figures quoted represent monthly changes (m/m) and are seasonally adjusted.